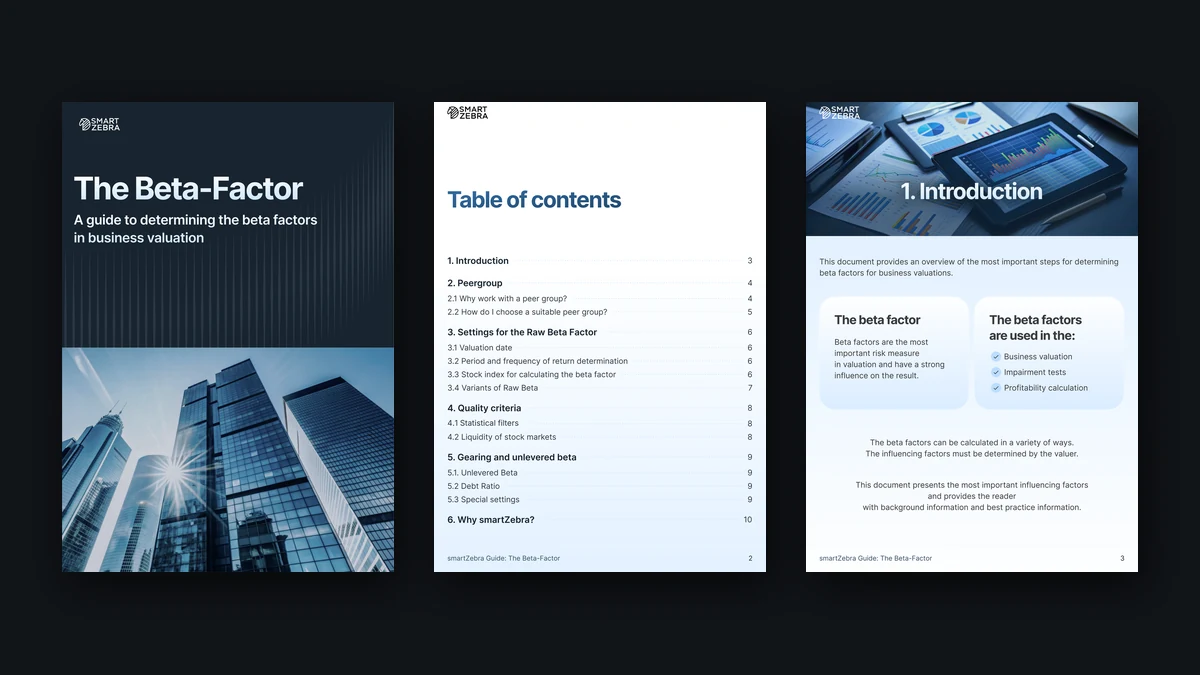
SEC-18

Telecom

The telecom sector has shifted noticeably this month: valued 7 % lower than in September, beta down 0.01 to 0.21.
Median multiple
13.0x
EV/EBIT (NTM)
▼ −7 % vs. Sep · was 14.0x
Dispersion (%)
23
Lower = tighter peer group
Beta
0.21
5y weekly
▼ −0.01 vs. Sep · was 0.21
WACC (%)
4.90
Sector cost of capital
Tax rate (%)
22.44
Peer average
← Swipe left or right to move through the sections →

What the numbers say.

The telecom sector has shifted noticeably this month. It is valued notably lower than a month ago: the median EV/EBIT fell to 13.0x while companies moved both ways, the beta eased to 0.21, and the cost of capital stands at 4.9 %. The sector is more unsettled than in September: the choice of peers and settings moves the value more than it did.

01
EV/EBIT is the multiple to use

It is the tightest of the multiples the fundamentals explain, a dispersion of 23 % across the 20 companies, and the companies are comparable in growth and ROCE. EV/Sales spreads by 31 % because it carries the margin differences with it.

02
The beta to use: 5 years, weekly, 0.21

Among the stable settings it has the tightest spread across the 20 companies; R² 10 %, 18 of 20 betas significant, less liquid group (median bid-ask spread 0.39 %). The smartZebra standard setting, 5 years monthly, has a dispersion of 45 %. The settings alone move the median beta from 0.07 to 0.26.

03
The settings matter

Ten of the twenty companies move the EV/EBIT median by −10 % to +17 %, the settings by up to 44 %. Telecom sits in the settings corner of the map.

04
EBITDA minus capex margin is not what the market pays for this month

The usual yardsticks for telecom: EBITDA minus capex margin and ROCE. EBITDA minus capex margin: rejected (rank correlation +0.30 with EV/EBITDA (NTM)). ROCE: rejected (rank correlation −0.46 with EV/EBIT (NTM)). No other key figure from the statements explains EV/EBITDA clearly either – the companies are priced on things the accounts do not show.

EV/EBIT (NTM): median 14.0x → 13.0x

12 more expensive · 8 cheaper
Nokia fell most (−19 %), Magyar Telekom Telecommunications rose most (+8 %).
{"m":[["Cellnex Telecom","42.2","45.3","+7%"],["Swisscom","22.5","24.1","+7%"],["Infrastrutture Wireless Italiane","18.6","20.0","+7%"],["Tele2","15.8","16.4","+3%"],["Vodafone Group","16.3","16.4","±0%"],["Telia Company","15.4","16.3","+6%"],["Royal KPN","14.8","15.7","+6%"],["Telenor","14.3","14.9","+4%"],["BT Group","13.1","14.2","+8%"],["Elisa","13.8","13.2","−4%"],["Telecom Italia","14.4","12.8","−11%"],["Telefónica","12.9","12.8","−1%"],["Nokia","15.7","12.8","−19%"],["Telefonaktiebolaget LM Ericsson","10.1","10.9","+8%"],["Orange","10.5","10.6","±0%"],["Airtel Africa","10.4","9.4","−9%"],["Hellenic Telecommunications Organization","9.4","9.0","−5%"],["Magyar Telekom Telecommunications","8.1","8.8","+8%"],["Deutsche Telekom","8.4","8.3","−1%"],["Telekom Austria","8.4","7.5","−11%"]],"b":[["Nokia","1.02","1.04",80],["Telefonaktiebolaget LM Ericsson","0.75","0.79",57],["Airtel Africa","0.47","0.48",50],["Cellnex Telecom","0.40","0.38",65],["Infrastrutture Wireless Italiane","0.34","0.36",45],["Hellenic Telecommunications Organization","0.37","0.34",47],["Telecom Italia","0.23","0.25",62],["Telekom Austria","0.27","0.25",48],["Deutsche Telekom","0.20","0.21",68],["BT Group","0.16","0.20",57],["Magyar Telekom Telecommunications","0.16","0.19",59],["Telenor","0.22","0.18",33],["Elisa","0.20","0.18",57],["Telia Company","0.20","0.16",49],["Vodafone Group","0.18","0.16",62],["Telefónica","0.15","0.15",64],["Royal KPN","0.09","0.08",47],["Orange","0.07","0.05",44],["Swisscom","0.07","0.03",35]],"w":["Telenor","Swisscom","Orange","Infrastrutture Wireless Italiane","Hellenic Telecommunications Organization"]}

Beta (5 years, weekly): median 0.21 → 0.21

18 of 20 significant
Each line runs from last month’s beta (light dot) to this month’s (blue dot), on the same beta setting.

Do the usual yardsticks hold this month?

The usual yardsticks for telecom, tested on the 20 companies this month.
EBITDA minus capex margin
Rejected
Rank correlation +0.30 with EV/EBITDA (NTM) · clear link from +0.60
ROCE
Rejected
Rank correlation −0.46 with EV/EBIT (NTM) · clear link from +0.60

Position on the sector map

This sector in gold, the other 19 sectors in blue. Dashed lines at 40 pp are illustrative.

Construction
34
24
Chemicals
49
47
Utilities
29
158
Telecom
28
44
Media
63
50
Travel & Leisure
55
69
Retail
41
48
Luxury
48
47
Consumer Goods
22
50
Logistics
39
61
Business Serv.
30
42
Aero & Defence
30
93
Electrical Eq.
33
42
Medtech
24
34
Pharma
34
48
IT Services
22
69
Semiconductors
53
31
Software
35
58
Automotive
30
27
Machinery
13
31
Telecom

How much the choices move the result

Beta and fit

R² (median)
10 %
Significant betas
18 of 20
Median bid-ask spread
0.39 %
Beta range across settings
0.07–0.26

What moves the value?

Change vs. prior month
−7 % vs. September
Peer impact on the median
−10 % to +17 %
Spread from peer choice (pp)
28
Spread from beta settings (pp)
44
Position on the sector map
Settings decide

Cost of capital

Cost of equity (CAPM)
“kE = rf + β · MRP”
rf = base rate, MRP = market risk premium, β = sector median beta.
WACC
“WACC = E/(D+E) · kE + D/(D+E) · kD · (1 − t)”
kD = base rate + credit spread; t = peer-average tax rate.
Tax rate
“t = average tax rate of the 20 peers”
Shown above as Tax rate (%).

Selection rules

Best-fit multiple
“lowest dispersion across the 20 companies”
The reference multiple is used only as a fallback.
Beta setting
“tightest spread among stable settings”
Replaces 5y monthly only if it passes the two-month rule.
Status
“|Δ value| ≤ 1 % and |Δ β| ≤ 0.03 → stable”
Up to ±5 % / ±0.06 → shifted a bit; beyond → shifted noticeably.

Scope

The 20 largest European listed companies by market value with core business in telecom operators and towers; primary listing on a European exchange; banks, insurers, financial services and real estate are excluded.
Telecom
Telecom operators
Towers
Universe
European listed companies
Core business
Telecom
Selection
20 largest by market value

Banks, insurers, financial services and real estate are excluded.

Data notes

Draft figures, pending approval. Valuation date 31.10.2026.

Status compares with 30.09.2026 on the same multiple and beta setting.

Beta setting changed from 5 years, monthly to 5 years, weekly; the beta move is measured on the new setting in both months.

Figures are medians of 20 companies; company-level values appear only in the change charts.

Source: smartZebra app. Start a free trial to run the numbers yourself.
Unlock Your 5 Days 100% Access.

Experience the power of the smartZebra engine risk-free. See how fast you can build a defensible peer group or calculate a compliant WACC.

Full platform access
No hidden fees
No credit card required